IRS Increases Half-Year 2026 Mileage Rates
The Internal Revenue Service (IRS) announced an increase in the 2026 optional standard mileage rate, effective mid-year. The revision responds to recent increases in fuel prices. The optional standard mileage rates are used to calculate the deductible costs of operating an automobile for business, charitable, medical purposes, or moving purposes.
On July 1, 2026, standard mileage rates for the use of cars, vans, pickup trucks, or panel trucks increased to 76 cents per business mile driven, up from 72.5 cents, which began January 1, 2026. Medical and moving rates climbed to 23.5 cents on July 1, 2026, up from 20.5 cents in the first half of 2026, while charitable organization rates remain at 14 cents per mile.
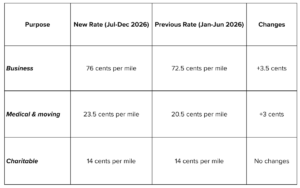
The standard mileage rate for business is based on an annual study of the fixed and variable costs of operating an automobile. The rate for medical and moving purposes is based on the variable cost from the annual study, and the charitable use is set by the statute.
Standard Mileage Rate Usage
The half-year increase in IRS mileage rates for 2026 applies to miles driven starting July 1, 2026. These standard mileage rates are important because they provide small businesses with a framework for calculating deductible costs for operating a vehicle for business purposes. Businesses can use these rates as a basis for reimbursing employees for mileage and for calculating mileage used on personal vehicles.
The IRS does give taxpayers the option of calculating the actual costs of using their vehicle rather than using the standard mileage rates. A business can choose either mileage or actual vehicle expenses, not both. Additionally, a taxpayer may not use the business standard mileage rate for a vehicle after using any depreciation method under the Modified Accelerated Cost Recovery System (MACRS) or after claiming a Section 179 deduction for that vehicle.
The standard mileage rates set forth in Notice 2026-10 continue to apply to deductible transportation expenses paid or incurred for business, medical, or moving expense purposes before July 1, 2026. This includes the mileage allowance paid to an employee before July 1, 2026 and transportation expenses paid or incurred by the employee before July 1, 2026.
For more information on the IRS 2026 mileage rates, see Part IV Optional Standard Mileage Rates Announcement 2026-11 IRS Article.
If you have questions about the information outlined above, McKonly & Asbury’s experienced professionals are here to help. Learn more about our Entrepreneurial Accounting Solutions (EAS) practice by visiting our Entrepreneurial industry page or by contacting a member of the EAS team.
This article was written by EAS Senior Accounting Consultant Maria Dicent-Hernandez under supervision of Supervisor Becky Lauffer.
About the Author

Becky Lauffer joined McKonly & Asbury in 2021 and is a Supervisor in the firm’s Entrepreneurial Accounting Solutions segment.
Becky provides outsourced accounting and tax services for a variety of clients, including small and family-owned businesses and nonprofit entities. She also assists with
accounts payable and receivable, monthly close, financial statement preparation, and QuickBooks.